Market overview and structural significance of Point Of Sale (POS) Software Market
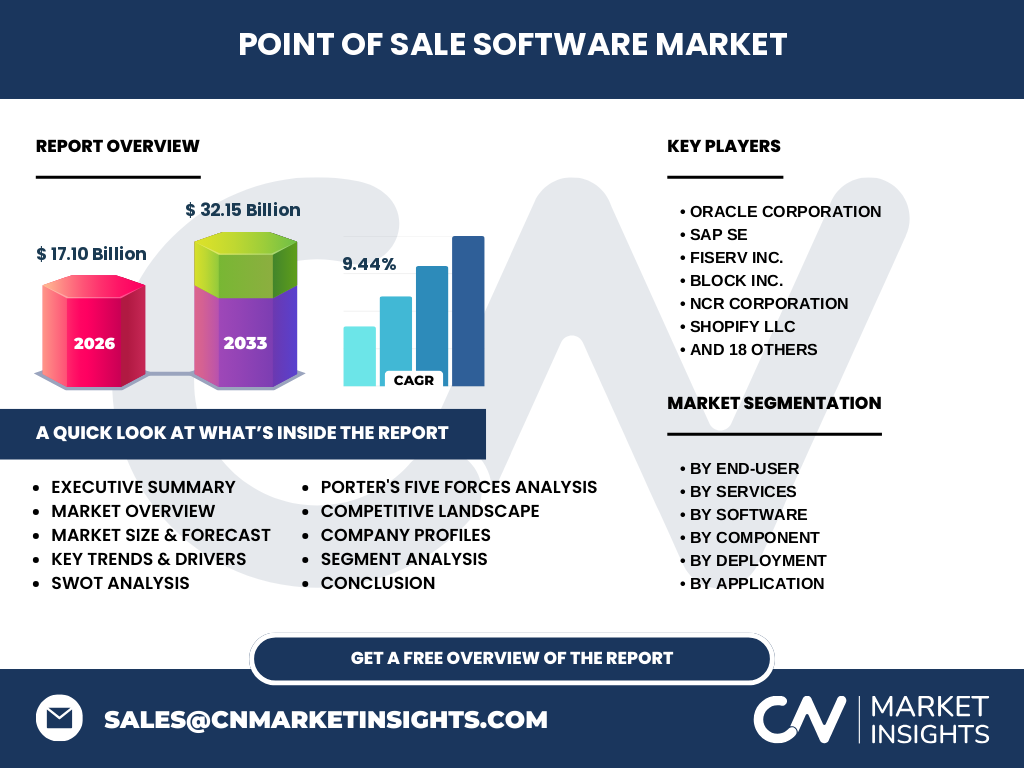
Our analysis indicates that the Point Of Sale (POS) Software Market plays a critical role in modern commerce, bridging frontline transactions with enterprise back-ends. Valued at 17.10 Billion in 2026, this sector encompasses specialized applications for inventory tracking, customer engagement, and payment processing. As regulatory compliance regarding fiscal data storage tightens under bodies like the European Union's tax authorities, advanced POS solutions have become indispensable for transactional transparency.
Key market drivers, restraints, challenges, and opportunities shaping Point Of Sale (POS) Software Market
The market is propelled by the rapid adoption of cloud architectures and omnichannel retail strategies. However, high implementation costs and fragmented regional payment gateways act as notable restraints. The primary challenge remains safeguarding sensitive cardholder data against sophisticated cyber threats. Opportunities abound in integrating artificial intelligence for predictive inventory management, which directly favors tech-forward vendors offering robust API connectivity.
The Shift Toward Omnichannel and Cloud Solutions in Point Of Sale (POS) Software Market
Emerging growth patterns highlight an aggressive pivot toward Cloud-Based POS Software and Mobile POS Software (mPOS). Retailers and hospitality operators increasingly demand seamless synchronization between physical storefronts and e-commerce platforms. This trend rewards vendors with superior e-commerce integration capabilities, enabling real-time stock visibility across warehouses and digital channels without manual data reconciliation.
COVID-19 impact analysis and recovery trajectory for Point Of Sale (POS) Software Market
The pandemic severely disrupted traditional brick-and-mortar retail and hospitality sectors, causing an initial contraction in hardware and legacy license sales. Conversely, it catalyzed an unprecedented surge in contactless payment integrations and curbside pickup modules. Recovery has been robust, as merchants prioritized digital resilience, permanently accelerating the transition from on-premises installations to flexible cloud-based architectures.
Competitive Benchmarking and Industry Concentration
The competitive landscape features a mix of legacy enterprise giants and agile fintech innovators. Market concentration is moderate yet polarizing, with established players like Oracle Corporation and SAP SE dominating large-scale retail, while dynamic innovators such as Toast Inc. and Shopify LLC capture high-growth SMB segments. Strategic partnerships with payment processors remain a primary differentiator for market share acquisition.
Executive Summary of Point Of Sale (POS) Software Market Findings
Our comprehensive research projects the Point Of Sale (POS) Software Market to reach 32.15 Billion by 2033, expanding at a robust CAGR of 9.44% from 2027. Growth is anchored by surging demand for multi-channel retailing, automated inventory tracking, and specialized vertical solutions in healthcare and government sectors.
Market forecast trajectory from 2027 to 2033
Based on our econometric modeling, the market will scale from its 2026 baseline of 17.10 Billion to achieve 32.15 Billion by 2033, maintaining a steady 9.44% CAGR. This trajectory is fueled by accelerated digital transformation initiatives across emerging economies and the continuous replacement of legacy terminals with intelligent software suites.
Segmentation analysis across end-users, services, software, component, deployment, and application
Segmentation reveals distinct operational priorities across industries.
- End-User: Retail, Healthcare, Government Sector, Media And Entertainment, Warehouses, Hospitality, Other End-Users.
- Services: Consulting, Installation, Training, Maintenance, Customization, Managed Services.
- Software: Transaction Management, Inventory Management, CRM, Sales Reporting, Payment Processing, Cloud-Based, Mobile, Multi-Channel, E-Commerce Integration.
- Component: Software, Services.
- Deployment: On-Cloud, On-Premises.
- Application: Inventory Tracking, Sales Reporting, Purchasing Management, Customer Engagement.
Regional market analysis and geographic performance distribution
Geographic performance varies significantly, driven by local regulatory frameworks, broadband infrastructure, and retail maturity. North America maintains the highest revenue share due to early adoption of cloud technologies and widespread contactless payment infrastructure. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, propelled by the rapid digitization of small and medium-sized enterprises in developing economies.
In-depth regional review of high-growth territories
Our analysis highlights that North America and Europe lead in regulatory-driven technology upgrades, such as fiscalization mandates. Conversely, markets in Latin America and Southeast Asia are leapfrogging traditional POS infrastructure, adopting mobile-first and cloud-native solutions directly. This creates fertile ground for regional specialists like Qashier PTE Ltd. and Foodics to capture localized market share.
Company profiles and strategic positioning of leading market participants
Industry leaders occupy distinct strategic niches. Oracle Corporation and SAP SE target enterprise-grade multi-national retailers with comprehensive ecosystem integration. Meanwhile, specialized innovators like Lightspeed Commerce, Revel Systems, and Epics Now focus on mid-market retail and hospitality agility, offering tailored vertical workflows that reduce friction for frontline staff.
Porter's Five Forces analysis of competitive intensity
Porter's framework reveals intense rivalry driven by a proliferation of SaaS vendors offering low initial switching costs. Threat of substitutes remains moderate, though specialized vertical requirements protect complex software. Bargaining power of buyers is high due to vendor abundance, compelling companies to continuously innovate in AI-driven analytics and seamless hardware-software integration.
SWOT analysis of the global POS software industry
Strengths include high recurring SaaS revenues and deeply embedded operational utility. Weaknesses involve vulnerability to data breaches and high customer acquisition costs. Opportunities lie in emerging market SME digitization and embedded fintech services. Threats stem from regulatory compliance fragmentation across global jurisdictions and macroeconomic headwinds affecting retail spending.
Value chain analysis from code development to end-user deployment
The value chain flows from software development kits and cloud infrastructure providers to POS vendors, channel partners, and ultimately end-users in retail and hospitality. Value capture increasingly concentrates at the software layer, particularly among vendors offering proprietary payment processing monetization alongside core transaction management.
Investment insights and high-potential strategic areas
Strategic investors should focus on vendors embedding financial services directly into their software stacks, such as embedded lending and integrated merchant accounts. Companies possessing robust APIs for E-Commerce Integration Software and advanced Customer Relationship Management (CRM) Software represent prime targets for high capital appreciation.
Conclusion and key takeaways for stakeholders
The Point Of Sale (POS) Software Market represents a highly lucrative arena projected to hit 32.15 Billion by 2033. Success in this ecosystem demands continuous feature evolution, particularly in cloud agility, omnichannel synchronization, and integrated payment processing, separating commoditized terminal providers from indispensable enterprise partners.
Research methodology for baseline estimations and triangulation
Our findings are derived from a rigorous triangulation methodology. We combine primary stakeholder interviews with C-level executives across retail and fintech sectors, secondary macroeconomic indicators, and trade registry databases. Financial models are cross-referenced with public earnings reports of major entities like Block Inc. and Shopify LLC to ensure absolute market sizing accuracy.
Scope of the report and coverage parameters
This report covers global market dynamics for the Point Of Sale (POS) Software Market from 2026 baseline data through the forecast period ending in 2033. The analysis evaluates software, services, deployments, and key end-user verticals globally, excluding standalone hardware manufacturing revenues except where bundled directly with software licensing agreements.
Recent developments, partnerships, and strategic corporate moves
Recent industry momentum is defined by aggressive M&A activity and platform expansions. Major players like Pine Labs and Toast Inc. have continuously rolled out enhanced merchant financing features and omnichannel modules. Strategic alliances between software providers and payment networks underscore the industry's race toward unified commerce solutions.